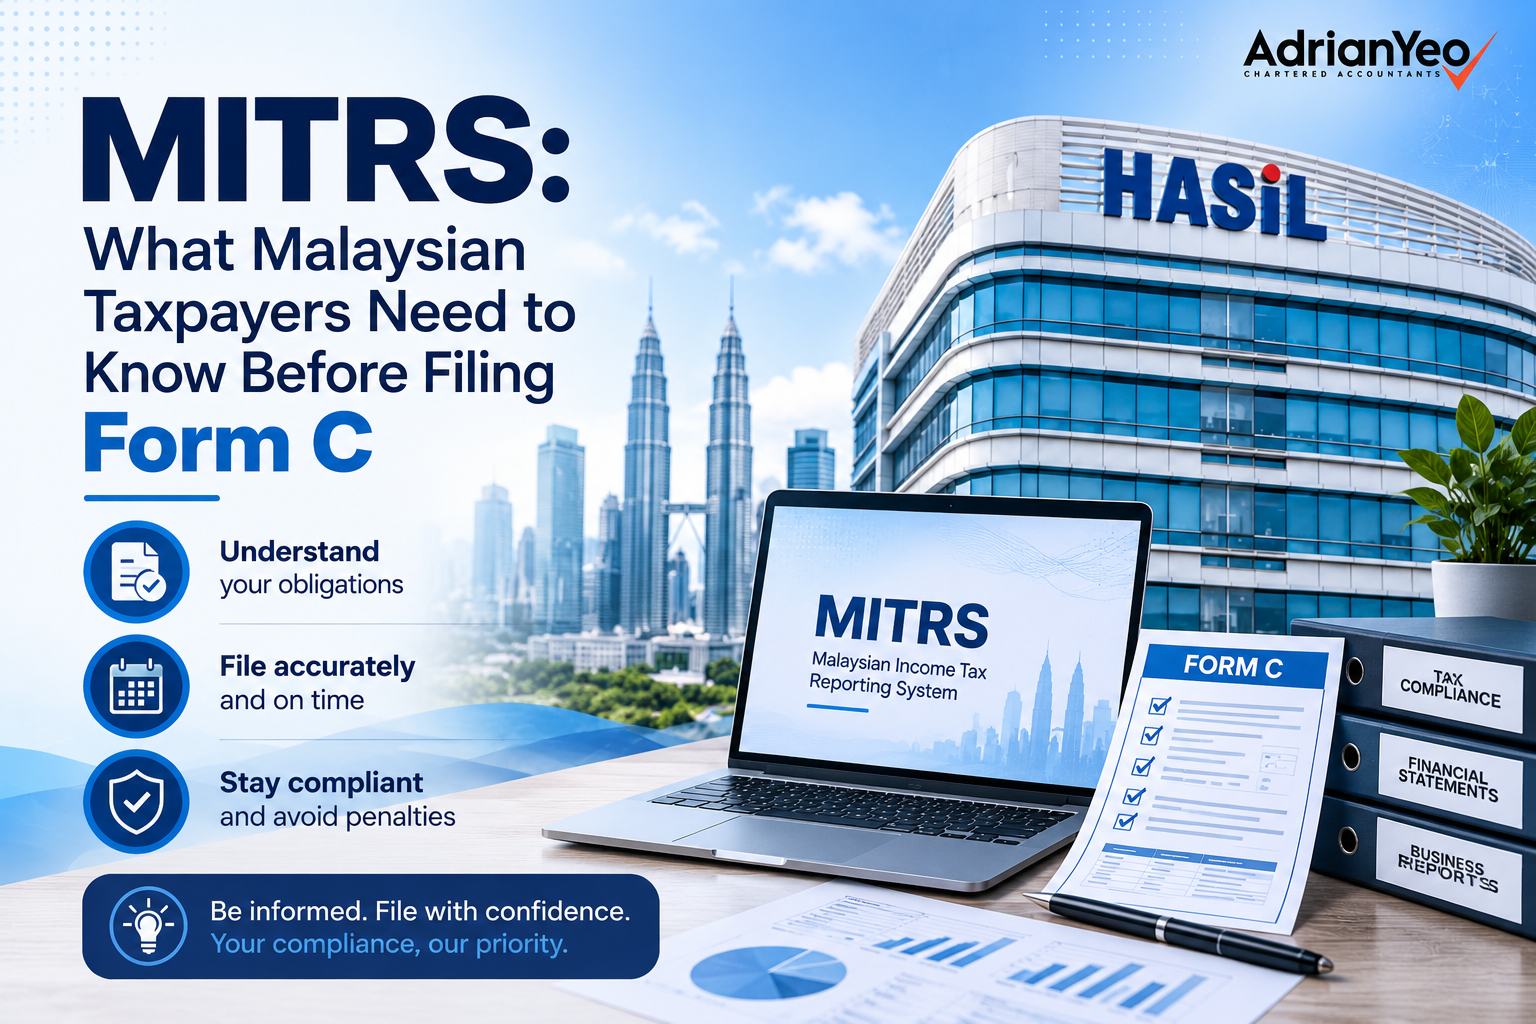

The Inland Revenue Board of Malaysia (IRB) continues to digitalize tax administration through the Malaysia Income Tax Reporting System (MITRS).
Beginning with corporate income tax submissions, MITRS requires companies to submit supporting tax documents electronically together with their Form C. This initiative aims to improve tax compliance, enhance audit efficiency, and enable data-driven tax administration.
Here’s what taxpayers should know.
What is MITRS?
The Malaysia Income Tax Reporting System (MITRS) is an electronic document submission platform where companies (or their appointed tax agents) upload supporting tax documents alongside their annual corporate income tax return (Form C).
Rather than requesting documents only during an audit, IRB will now receive key tax information upfront in a standardized digital format.
Why is IRB Introducing MITRS?
MITRS supports IRB’s move towards a more technology-driven tax administration.
By receiving tax documents electronically, IRB can:
- Cross-check audited financial statements against Form C more efficiently.
- Detect inconsistencies earlier.
- Integrate information with other government agencies such as SSM and financial institutions.
- Enhance risk assessment through digital and AI-assisted analytics.
This marks another step towards smarter and more efficient tax administration in Malaysia.
Taxpayer Responsibilities Under Section 82B
Under Section 82B of the Income Tax Act 1967, taxpayers are required to submit prescribed documents through MITRS together with their tax return.
MITRS currently consists of two modules:
Section 82B Module
Mandatory submission of supporting tax information together with Form C.
Section 80/81 Module
Submission of additional documents when specifically requested by IRB during tax audits or investigations.
Documents Required for MITRS Submission
Depending on the taxpayer’s circumstances, documents generally include:
- Audited Financial Statements
- Directors’ Report
- Tax Computation
- Capital Allowance & Charges Schedule (where applicable)
- Incentive Computation (where applicable)
All documents must be submitted in PDF format (Malay or English), with a combined file size not exceeding 20MB per taxpayer per year of assessment.
What Happens If You Don’t Comply?
Failure to submit documents through MITRS—or submitting incomplete documentation—may expose taxpayers to penalties under Section 120(1)(d) of the Income Tax Act 1967.
Potential consequences include:
- Fine ranging from RM2,000 to RM20,000, or
- Imprisonment of up to six months, or both.
Even an incomplete financial statement submission may be regarded as non-compliance.
Important MITRS Submission Timeline
For companies with a statutory filing deadline of 31 December 2025, the corresponding MITRS submission deadline is 30 January 2026.
Where a one-month filing grace period or an approved extension of time applies, the MITRS submission deadline is similarly extended.
Taxpayers should ensure supporting documents are prepared early to avoid last-minute issues.
Key Takeaway
MITRS is more than just another filing requirement—it represents a significant shift in how tax compliance is managed in Malaysia.
Preparing tax computations, audited accounts and supporting schedules in advance will help ensure smoother submissions and reduce compliance risks.
Companies are encouraged to review their document readiness well before their filing deadline.