
As Malaysia’s tax reporting landscape continues to evolve, businesses and tax professionals are increasingly encountering two important reporting systems: MBRS (Malaysian Business Reporting System) and MITRS (Malaysian Income Tax Reporting System).
Although both systems involve digital reporting, they serve different purposes and are administered by different authorities. Understanding these distinctions is essential to ensure compliance and avoid unnecessary reporting errors.
What is MBRS?
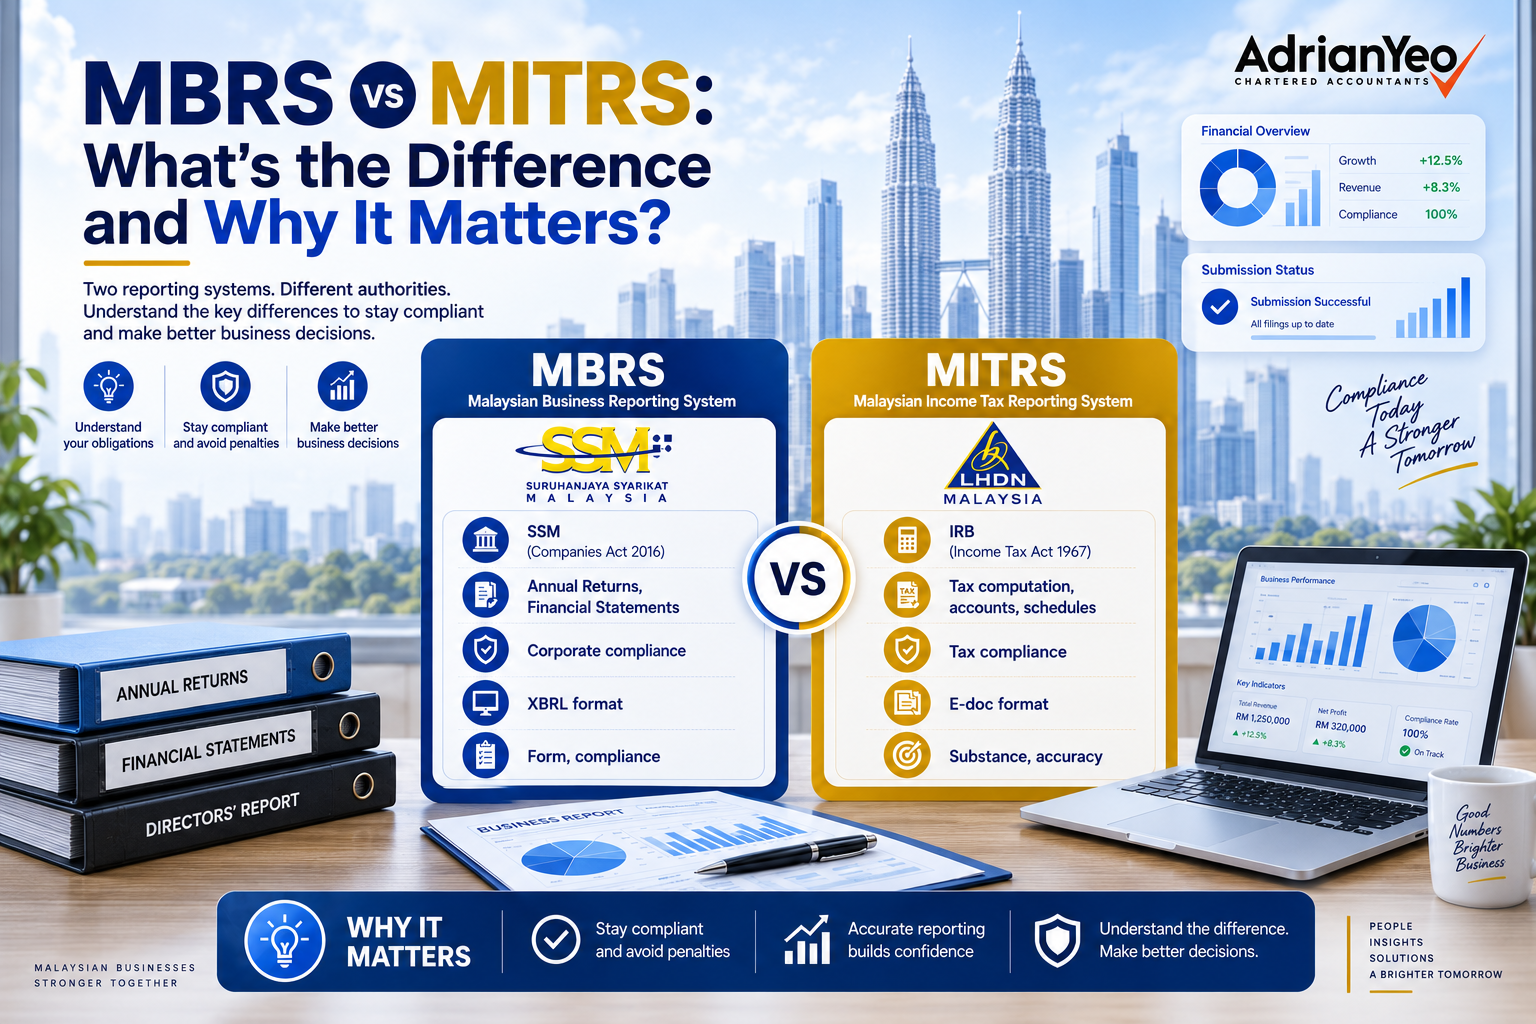
The Malaysian Business Reporting System (MBRS) is an online platform introduced by the Companies Commission of Malaysia (SSM). It enables companies to submit statutory documents in XBRL (eXtensible Business Reporting Language) format.
MBRS is primarily used for:
- Financial Statements (FS)
- Annual Returns (AR)
- Exemption Applications (EA)
Its objective is to standardise corporate reporting while improving the quality, transparency, and efficiency of company filings.
What is MITRS?
The Malaysian Income Tax Reporting System (MITRS) is introduced by the Inland Revenue Board of Malaysia (LHDN) to facilitate digital submission of tax-related information.
MITRS adopts the XBRL format for tax reporting, allowing taxpayers to submit structured financial and tax data electronically. The initiative supports greater accuracy, consistency, and automation in tax administration.
MBRS vs MITRS: Key Differences
|
MBRS |
MITRS |
|
Administered by SSM |
Administered by LHDN |
|
Focuses on statutory corporate filings |
Focuses on income tax reporting |
|
Used for Financial Statements, Annual Returns |
Used for Tax Computation and Tax Reporting |
|
Supports corporate compliance |
Supports tax compliance |
| XBRL-based reporting |
XBRL-based reporting |
Why Should Businesses Prepare?
As regulatory authorities continue to digitalise reporting requirements, organisations should begin preparing by:
- Understanding the reporting requirements for both systems.
- Ensuring financial data is accurate and consistent.
- Reviewing existing accounting and reporting processes.
- Equipping finance and tax teams with the necessary knowledge.
- Adopting digital reporting tools that support XBRL submissions.
Early preparation will help minimise compliance risks and reduce last-minute implementation challenges.
Stay Ahead of Regulatory Changes
Digital reporting is becoming the new standard in corporate and tax compliance. Whether you’re responsible for statutory filings under MBRS or tax submissions through MITRS, understanding both frameworks will help your organisation remain compliant and future-ready.
Keep following our updates for practical insights, regulatory developments, and guidance on Malaysia’s evolving reporting requirements.