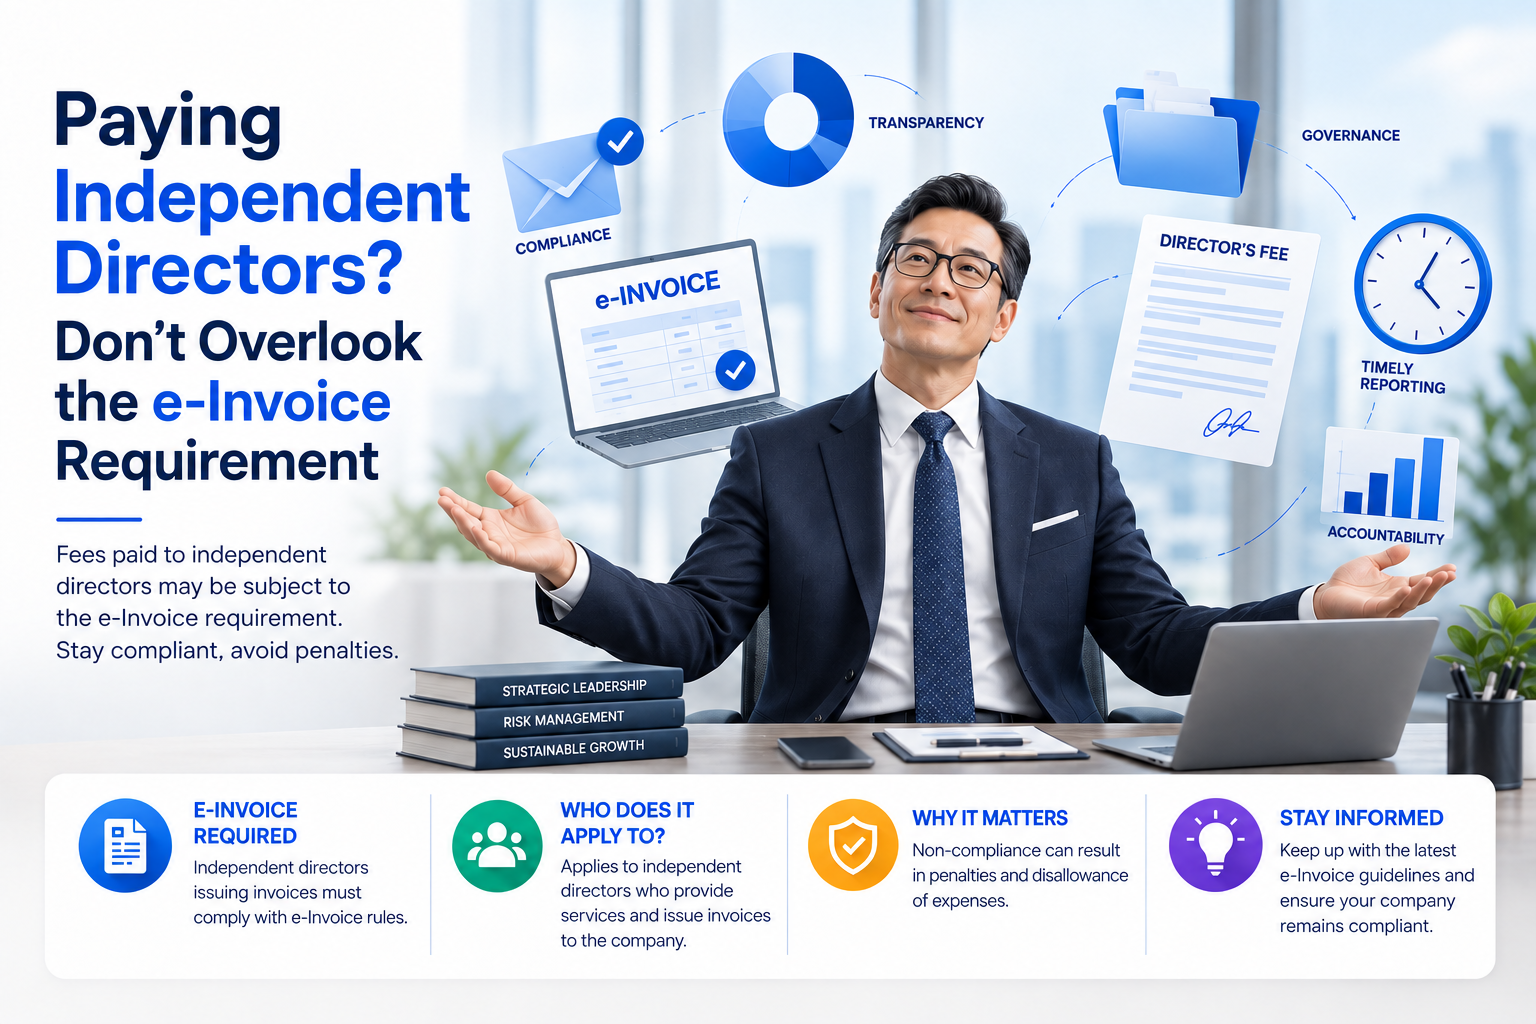

With e-Invoice now being implemented in Malaysia, businesses need to pay attention not only to sales and purchases, but also to payments made to independent directors.
A common question is:
“If we pay fees to an independent director, who should issue the e-Invoice?”
The answer depends on the nature of the relationship between the company and the director.
Independent Director Under a Contract for Service (independent contractor)
Where an independent director provides services to the company under a contract for service, the director is generally required to issue an e-Invoice to the company for the director’s fees.
In other words:
Company pays independent director → Independent director issues e-Invoice to the company.
The director does not necessarily need to be registered with SSM for this purpose.
According to the Inland Revenue Board of Malaysia (HASiL), an individual director who is not registered with SSM may issue the e-Invoice under his or her own name and MyKad number, where applicable.
What If the Director Is Under a Contract of Service (employer-employee)?
This situation is different.
Where the payment relates to an individual who is engaged under a contract of service, the income is treated as employment income. This means that the Company is paying the Director a salary, and all respective statutory contributions (EPF, SOCSO, EIS).
Employment income is currently among the income types that are not required to be supported by an e-Invoice.
Therefore, the company would not require an e-Invoice from the individual for that employment income.
Contract for Service vs Contract of Service
|
Arrangement |
e-Invoice Treatment |
| Independent director under contract for service (independent contractor) | Director issues e-Invoice to the company |
| Director under contract of service (employer-employee) | No e-Invoice required for the employment income |
| Director is not registered with SSM | Does not automatically mean the company must issue a self-billed e-Invoice |
What Should Companies Do?
Before processing director’s fees, companies should first determine the nature of the arrangement.
Consider the following:
- Review the director’s appointment/engagement arrangement
Determine whether the services are provided under a contract of service or contract for service. - Identify the correct e-Invoice issuer
For an independent director providing services under a contract for service, the director should issue the e-Invoice to the company. - Ensure the director has the required information
The director should provide the necessary details for e-Invoice issuance, including the relevant identification information. - Keep proper supporting documents
Companies should retain the appointment letter, agreement, payment records and e-Invoice as appropriate to support the payment.
Don’t Assume Every Director’s Fee Is Treated the Same
The term “director’s fee” alone does not determine the e-Invoice treatment.
The important question is:
What is the nature of the relationship between the company and the individual?
If the independent director is providing services under a contract for service, an e-Invoice is generally required from the director.
Understanding the distinction can help companies avoid incorrectly issuing self-billed e-Invoices or overlooking the e-Invoice obligation of the service provider.
Key Takeaway
Paying an independent director? Check the contract before deciding who needs to issue the e-Invoice.
Contract for service → Director issues e-Invoice
Contract of service → Employment income; e-Invoice is not required
Businesses should review their director remuneration arrangements and ensure the e-Invoice treatment is correctly applied.